

E-invoicing in Germany: What needs to be done by 1 January 2027
Many companies have already set up an email inbox for receiving invoices. On its own, however, this is generally not enough to ensure legally compliant implementation.
Electronic invoicing in France: A pragmatic approach during the launch phase
France’s e-invoicing reform is live. Good-faith businesses facing launch issues benefit from a proportionate approach, without any delay to deadlines.
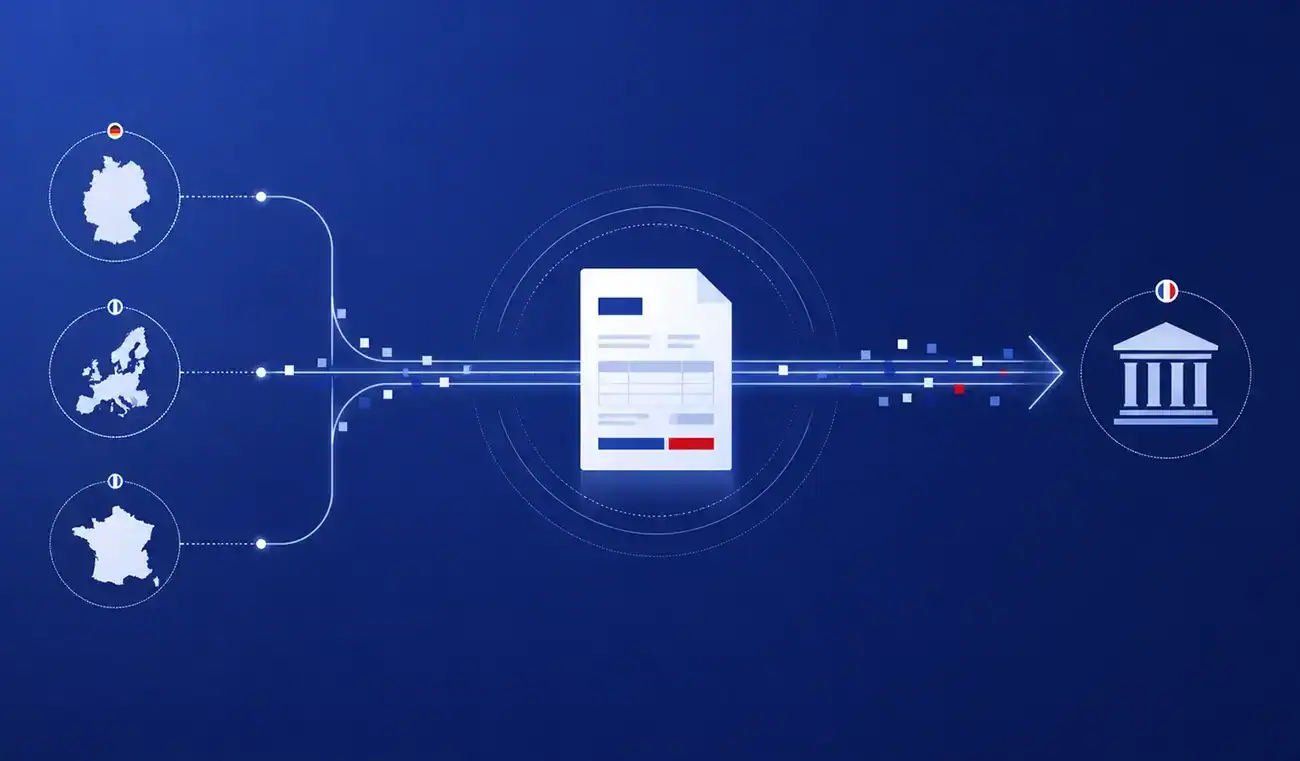
French e-reporting from September 2026: what foreign companies need to check now
Foreign businesses that store goods in Germany or supply German private customers are often subject to German VAT obligations even though they do not have an establishment there. T

E-Reporting for Foreign Companies Without a Fixed Establishment in France
Foreign companies without a permanent establishment in France are not subject to the e-invoicing requirement, but may be subject to the e-reporting requirement.

VAT on cross-border services in France
For VAT purposes, what matters is not where the service is physically performed, but where it is deemed to be located for tax purposes. This territoriality rule determines which co

Input VAT Deduction from Advance Payment Invoices
The German Federal Fiscal Court has further clarified the requirements for input VAT deduction from advance payment invoices. The decision is particularly relevant for companies ma

Update: Tax-Free Crisis Bonus Put on Hold for the Time Being
The planned tax-free and social-security-free relief bonus of up to €1,000 for employees will not be introduced for the time being. Although the German Bundestag passed the draft

Update: Tax-Free Crisis Bonus of €1,000 in Germany
With the planned introduction of a tax-free relief payment for employees, the legislator is creating a new option to provide financial support to employees. The measure is designed

Tax-Free Crisis Bonus – Brief Overview of the Planned Relief Measure
The German Federal Government is planning to introduce a tax-free crisis bonus of up to EUR 1,000 for the year 2026. Employers are expected to be given the option of granting this

Transfer pricing documentation
The amendments to transfer pricing documentation introduced by the Fourth Bureaucracy Relief Act already apply as from 2025; however, they will become fully relevant in practice pa


